A waterfall distribution looks simple on the term sheet: return of capital, preferred return, then a promote split. It stops looking simple the first time a partial capital call, a mid-year distribution, and a catch-up provision all land in the same quarter, and the spreadsheet that has worked fine for two years suddenly cannot tell you who is owed what.
This guide covers how waterfall structures work, where the calculations break down, and what investor reporting needs to get right once a fund has more than a handful of investors and more than one distribution event a year.
What is a distribution waterfall?
A waterfall is the agreed order in which cash gets distributed to investors and sponsors as a deal or fund generates returns. It exists to align sponsor compensation with investor outcomes: the sponsor earns more as investors do better, and the order of payments protects investor capital before the sponsor participates meaningfully in the upside.
A typical structure runs through tiers.
- Return of capital. Investor capital contributions are returned first, before any profit is distributed.
- Preferred return. Investors receive a stated return, often 6 to 10 percent annually, on their invested capital before the sponsor participates in profit.
- Catch-up. The sponsor receives a disproportionate share of distributions until their cumulative share reaches the agreed promote percentage of total profit distributed so far.
- Promote split. Remaining distributions are split between investors and sponsor according to the agreed carried interest, often escalating through further tiers as returns increase.
Structures vary from this baseline in ways that matter: some are calculated deal by deal, others at the fund level across all deals; some include multiple promote tiers tied to escalating return hurdles; some include a European waterfall requiring full return of capital across the fund before any promote, while an American waterfall calculates promote deal by deal.
Why do waterfall calculations break down?
The arithmetic within a single, static distribution is not difficult. The difficulty is that real distributions are rarely single or static.
Multiple distribution events with different timing
A fund with quarterly distributions across a five-year hold has twenty distribution events, each requiring the cumulative preferred return to be recalculated to that date. Spreadsheets built for one calculation get copied forward and drift from the correct cumulative basis with each iteration.
Capital calls at different times for different investors
When investors fund on different schedules, or a late-closing investor funds a smaller share of an earlier call, the capital base each investor’s preferred return accrues against is no longer uniform. Getting this right requires tracking capital account balances per investor, not a single fund-level capital figure.
Catch-up provisions with a stated end point
A catch-up tier runs until the sponsor’s cumulative share reaches a specific percentage of profit distributed to date, not for a fixed dollar amount. Recalculating that threshold correctly at each distribution, against the cumulative history, is where manual models most often go wrong.
Multiple promote tiers
Structures with escalating hurdles, for example a higher promote share above a 15 percent IRR than above an 8 percent IRR, require tracking which tier each dollar of distribution falls into, cumulatively, as returns compound over the hold period.
Clawback provisions
Some structures allow investors to reclaim excess promote paid to the sponsor if overall fund performance falls short at the end of the hold. Calculating a potential clawback requires the full distribution history to be reconstructible at any point, rather than only the current balance.
What does automated waterfall modelling change?
Calculations run from investor-level capital accounts
Each investor’s contributions, distributions and accrued preferred return are tracked individually rather than assumed uniform across the fund. This is the foundation everything else depends on.
Cumulative thresholds recalculate automatically
Catch-up tiers and promote hurdles reference the full distribution history rather than the current period alone, so the threshold test is correct at every distribution regardless of how many have preceded it.
Multiple structures are supported per fund or deal
A firm running both European and American waterfalls across different vehicles needs a system that holds the structure as configuration rather than hard-coded logic, since the calculation method genuinely differs.
Every distribution retains a full audit trail
When an investor or auditor asks how a specific distribution was calculated, the answer is the tier-by-tier calculation as it stood at that date, not a reconstruction from memory.
What investor reporting needs to deliver
The waterfall calculation is only useful if investors can see the result clearly and trust it. Five elements make reporting defensible.
- Capital account statements showing contributions, distributions, preferred return accrued and current balance per investor, updated with each event.
- Distribution notices that show the tier-by-tier calculation rather than only the final amount, so an investor can verify the math against their own capital account.
- Performance reporting including IRR and equity multiple calculated at the investor level, which differs from the deal-level or fund-level figure once timing and tier effects are accounted for.
- A secure portal giving investors on-demand access to statements, K-1s or equivalent tax documents, and reporting history, rather than requiring a request each time.
- Consistency across the portfolio so an investor holding positions in multiple deals or funds sees calculations built the same way in every one.
The distribution notice is where most disputes originate, and it is the easiest one to fix. A notice showing only the total amount invites a query about how it was derived. A notice showing each tier and the cumulative basis it was calculated against usually does not.
Where waterfall reporting connects to the rest of the portfolio
Distribution capacity is a function of what the underlying assets actually generate, which means waterfall accuracy depends on data that originates outside the fund-accounting function.
When property management and investment reporting run on the same platform, the NOI and cash flow figures feeding a distribution calculation are the same figures the property team is working from, rather than a periodic export reconciled separately.
For firms whose funds hold development projects alongside stabilised assets, the same connection extends back to the development stage, where distributable cash flow depends on project completion and cost-at-completion projections that live in the development records.
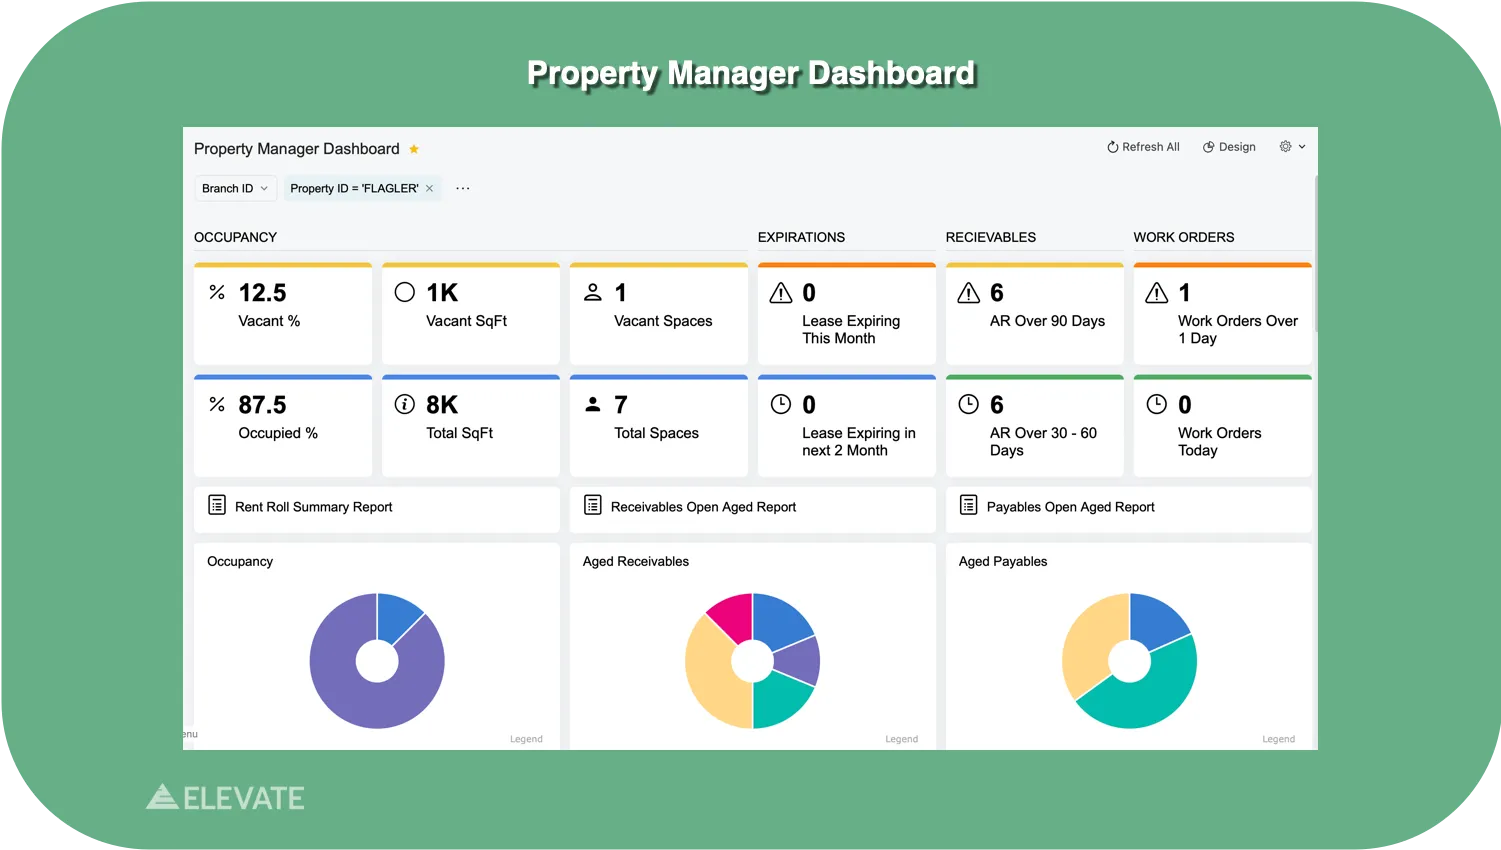
Elevate’s real estate investment management software holds waterfall modelling and investor reporting within the same dataset as the underlying asset performance.
Elevate is built on Acumatica, whose project and financial accounting layer supports multi-entity fund and asset structures within the same platform.
What to evaluate in a waterfall and investor reporting platform
- Model a distribution with a catch-up tier and show the full cumulative calculation behind the result.
- Show me an investor-level capital account with contributions, distributions and accrued preferred return.
- Configure both a European and an American waterfall and show how the calculation differs.
- Show me a distribution notice as an investor would receive it.
- Model a potential clawback scenario using the full distribution history.
- Show me investor-level IRR alongside deal-level IRR for the same investment and explain the difference.
The clawback question is the most demanding, and the most revealing. A platform that can reconstruct the full distribution history to test a clawback scenario is holding the data with real integrity. One that cannot is holding current balances only.
Getting it right
Waterfall accuracy is not really a calculation problem. It is a data integrity problem: whether investor-level capital accounts, distribution history and the underlying asset performance all derive from one consistent record.
Firms that get this right can answer any investor question about any distribution from the system, on the call. Firms that do not spend the days before every investor meeting reconstructing the numbers to make sure the spreadsheet still agrees with itself.
Elevate is an Acumatica Gold Certified Partner founded by CPAs, with nearly 40 years working with real estate investment firms. Book a 20-minute discovery call to see waterfall modelling on live fund data.